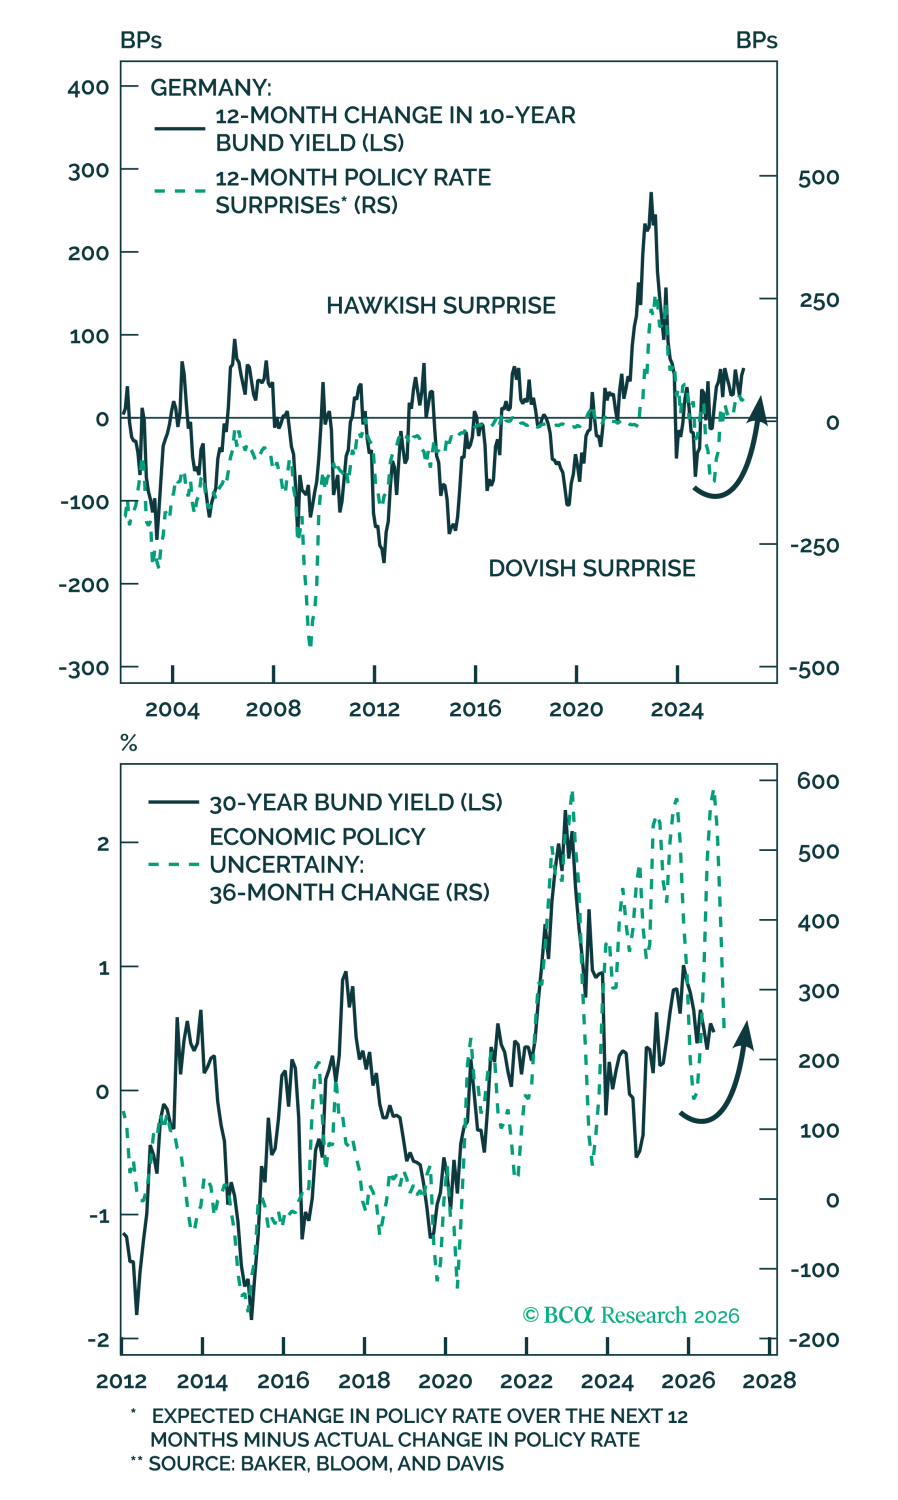
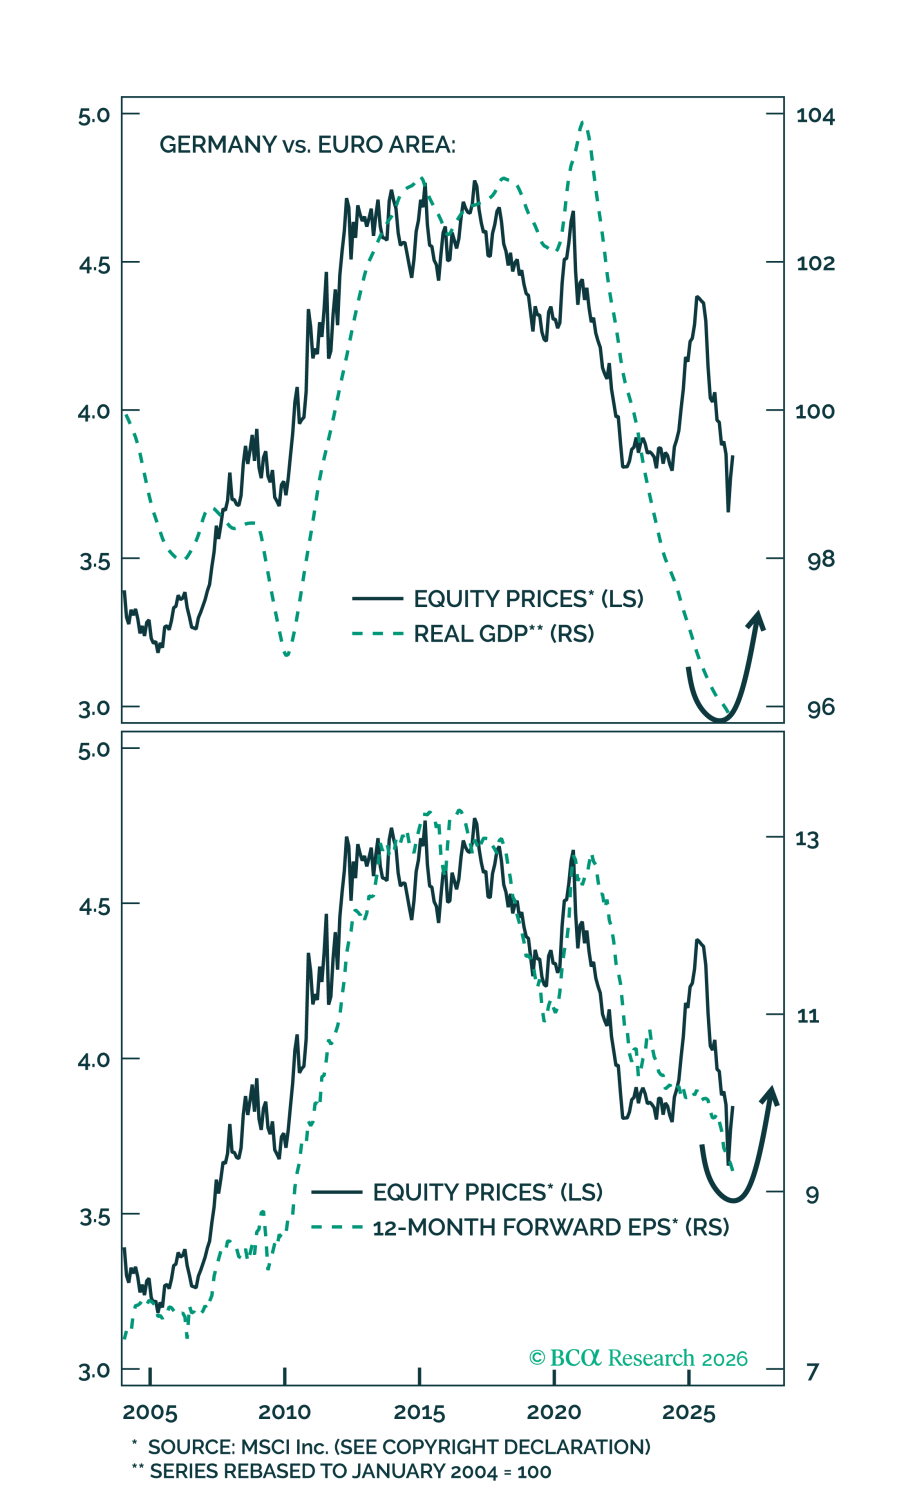
AfD’s recent sweeping result in Saxony-Anhalt has unsettled Germany’s political establishment, even if it does not put the party on the brink of national power. Instead, it brings Germany’s double reckoning into focus: a political backlash against weak growth, high living costs and a strained policy status quo, alongside a market-led reassessment of the country’s fiscal and monetary outlook. As higher oil prices revive inflation concerns and Bund yields climb through the post-QE adjustment, Berlin faces growing pressure to deliver a more forceful fiscal and pro-growth response. AfD won about 44% of the vote and 39 of 83 seats- three short of an outright majority. With other parties still refusing to cooperate, it cannot govern alone. The result is a landmark, but Saxony-Anhalt is a small, poorer eastern state where anti-establishment sentiment runs stronger than in Germany as a whole; the political fallout from the 2024 Magdeburg attack also amplified local concerns around immigration, security and law and order. Nationally, AfD polls around 28%, ahead of the CDU/CSU at roughly 20–21%, while the centre-left remains divided. Even so, its route to federal power is constrained by coalition arithmetic and the mainstream parties’ continuing refusal to work with it. With the next federal election only due in 2029, the government has time (and every incentive) to tackle the grievances driving support for populist parties: weak growth, elevated household costs, high taxes, bureaucracy, migration and public security. The more likely outcome is a mainstream policy reset: stronger border and domestic-security measures, fiscal support for households and firms, tax relief, deregulation and a renewed push to improve industrial competitiveness. Germany’s comparatively modest debt and deficit levels provide room to act. Planned federal net borrowing rises from €98.0 billion in 2026 to €118.7 billion in 2027, €148.8 billion in 2028 and €152.0 billion in the 2029 election year. A more supportive fiscal stance makes both political and economic sense, helping to cushion the energy shock and trade uncertainty while addressing the economic frustration that has boosted AfD support. It could also bring reforms investors have long wanted (lower taxes, faster permitting, reduced regulation and a more practical industrial and energy policy) without challenging Germany’s commitments to the EU, NATO and the euro area. Politics is part of the German equation, but for markets the more immediate focus is the rise in Bund yields. German 10-year borrowing costs have climbed to their highest level since 2009, reflecting a global bond sell-off and the market’s reassessment of a country that is simultaneously facing more fiscal issuance, higher energy costs and the residual effects of a decade of European Central Bank asset purchases. The ECB’s challenge now extends beyond the timing of its next rate move. After years of using asset purchases to hold down term premia, it must manage a gradual balance-sheet normalisation while oil-driven inflation keeps pressure on the policy outlook. |