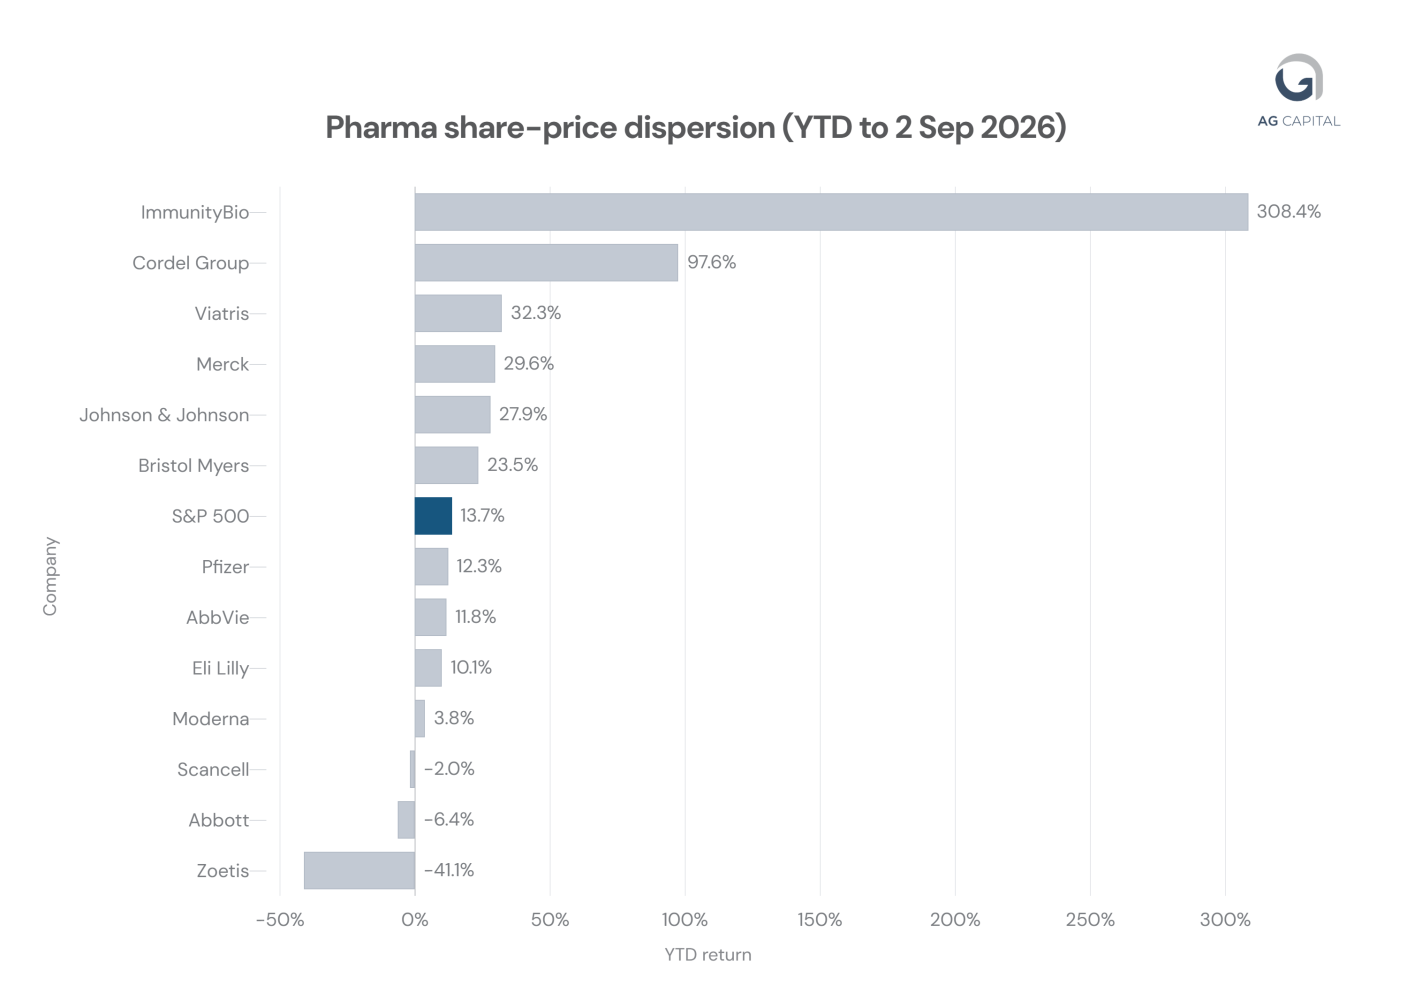
For much of the past several years, the pharmaceutical investment narrative has been unusually concentrated. First came COVID-19 vaccines and antivirals; then came GLP-1 medicines for diabetes and obesity. However, the focus is now moving beyond those headline themes, with growing momentum in oncology, immunology, diagnostics and personalised medicine. Global spending on cancer medicines reached $252 billion at list prices in 2024 and is projected to rise to $441 billion by 2029, reflecting both increased treatment volumes and the adoption of more advanced therapies. The investment case is highly differentiated across the sector. Pharma includes mature, cash-generative businesses, companies managing patent cycles, clinical-stage biotechs with binary outcomes, and medtech firms whose growth is tied to diagnostics rather than treatment. That spread is reflected in valuations: the larger, established groups in the peer set trade on forward earnings multiples, while Moderna, ImmunityBio and Scancell do not, with their valuations hinging instead on regulatory progress and a credible route to profitability. Cancer remains the industry's deepest and most technically demanding opportunity set. The direction of travel is away from broad cytotoxic therapies and toward more tailored interventions: targeted drugs matched to tumour biology, antibody-drug conjugates, radioligand therapies, cell therapies and combinations designed to enhance the patient's own immune response. The FDA's Centre for Drug Evaluation and Research approved 46 novel medicines in 2025, and oncology accounted for 14 of those approvals, underlining how central cancer remains to the development pipeline. ImmunityBio illustrates the rewards available when differentiated immuno-oncology assets begin to move from promise to commercial validation. Its lead product, Anktiva, is being developed and commercialised in bladder cancer, including BCG-unresponsive non-muscle-invasive disease. The company generated about $113 million of net product revenue in 2025, up roughly 700% year on year, and the FDA accepted a supplemental biologics licence application in May 2026 for expanded use of the product. Those milestones helped drive a 308.4% year-to-date share-price gain through 2 September 2026, showing how sharply markets can reprice concentrated biotech stories when data, regulation and commercial traction start to align. The post-pandemic legacy of mRNA may extend far beyond infectious disease. Moderna's work with Merck on intismeran autogene, formerly mRNA-4157/V940, offers one of the clearest proof-of-concept cases for personalised cancer vaccination. In a Phase 2b study in high-risk resected melanoma, the combination with Keytruda reduced the risk of recurrence or death by 49% versus Keytruda alone at a median five-year follow-up. Multiple Phase 2 and Phase 3 studies are under way across melanoma, non-small-cell lung cancer, bladder cancer and renal-cell carcinoma. Moderna is increasingly being read as an oncology and platform play rather than a fading COVID franchise, though the path there has been messy. The company weathered guidance cuts, vaccine-related regulatory uncertainty and a failed late-stage CMV vaccine, took a $1.5 billion loan from Ares Management, and saw the FDA initially balk at reviewing its flu-shot application before approving mFlusiva in August 2026 - the first mRNA flu vaccine cleared for US adults 50 and older. The clearest evidence, though, came from oncology: melanoma-vaccine data sent the stock up about 177% in a single session on 20 August, reportedly the largest one-day gain ever for an S&P 500 stock. Even so, Moderna was up just 3.8% year to date through 2 September, a sign of how deep the prior drawdown had been. On a different point of this continuum sits Scancell. Its iSCIB1 programme in advanced melanoma reported 77% progression-free survival at 20 months in combination with ipilimumab and nivolumab in the Phase 2 SCOPE trial. The company received FDA Fast Track designation in April 2026, followed by UK MHRA clearance in August for a Phase 3 registrational trial expected to enrol 550 patients. The innovation cycle also extends beyond therapeutics, however. Earlier diagnosis can reshape treatment pathways, improve outcomes and create the patient-identification infrastructure required for precision medicine. Abbott Laboratories represents the diagnostic side of this theme. In April 2026, it reduced full-year profit guidance to reflect the dilutive effect of a $21 billion cancer-screening acquisition, then reported second-quarter adjusted EPS of $1.31 versus a $1.28 consensus estimate and raised guidance to $5.45 to $5.60 per share. For investors, however, the opportunity set is expanding faster than returns are converging. Pharma covers everything from mega-cap, earnings-anchored franchises to loss-making, single-catalyst biotechs whose share prices can move by triple digits in a single trading session, as both ImmunityBio and Moderna have shown this year. |